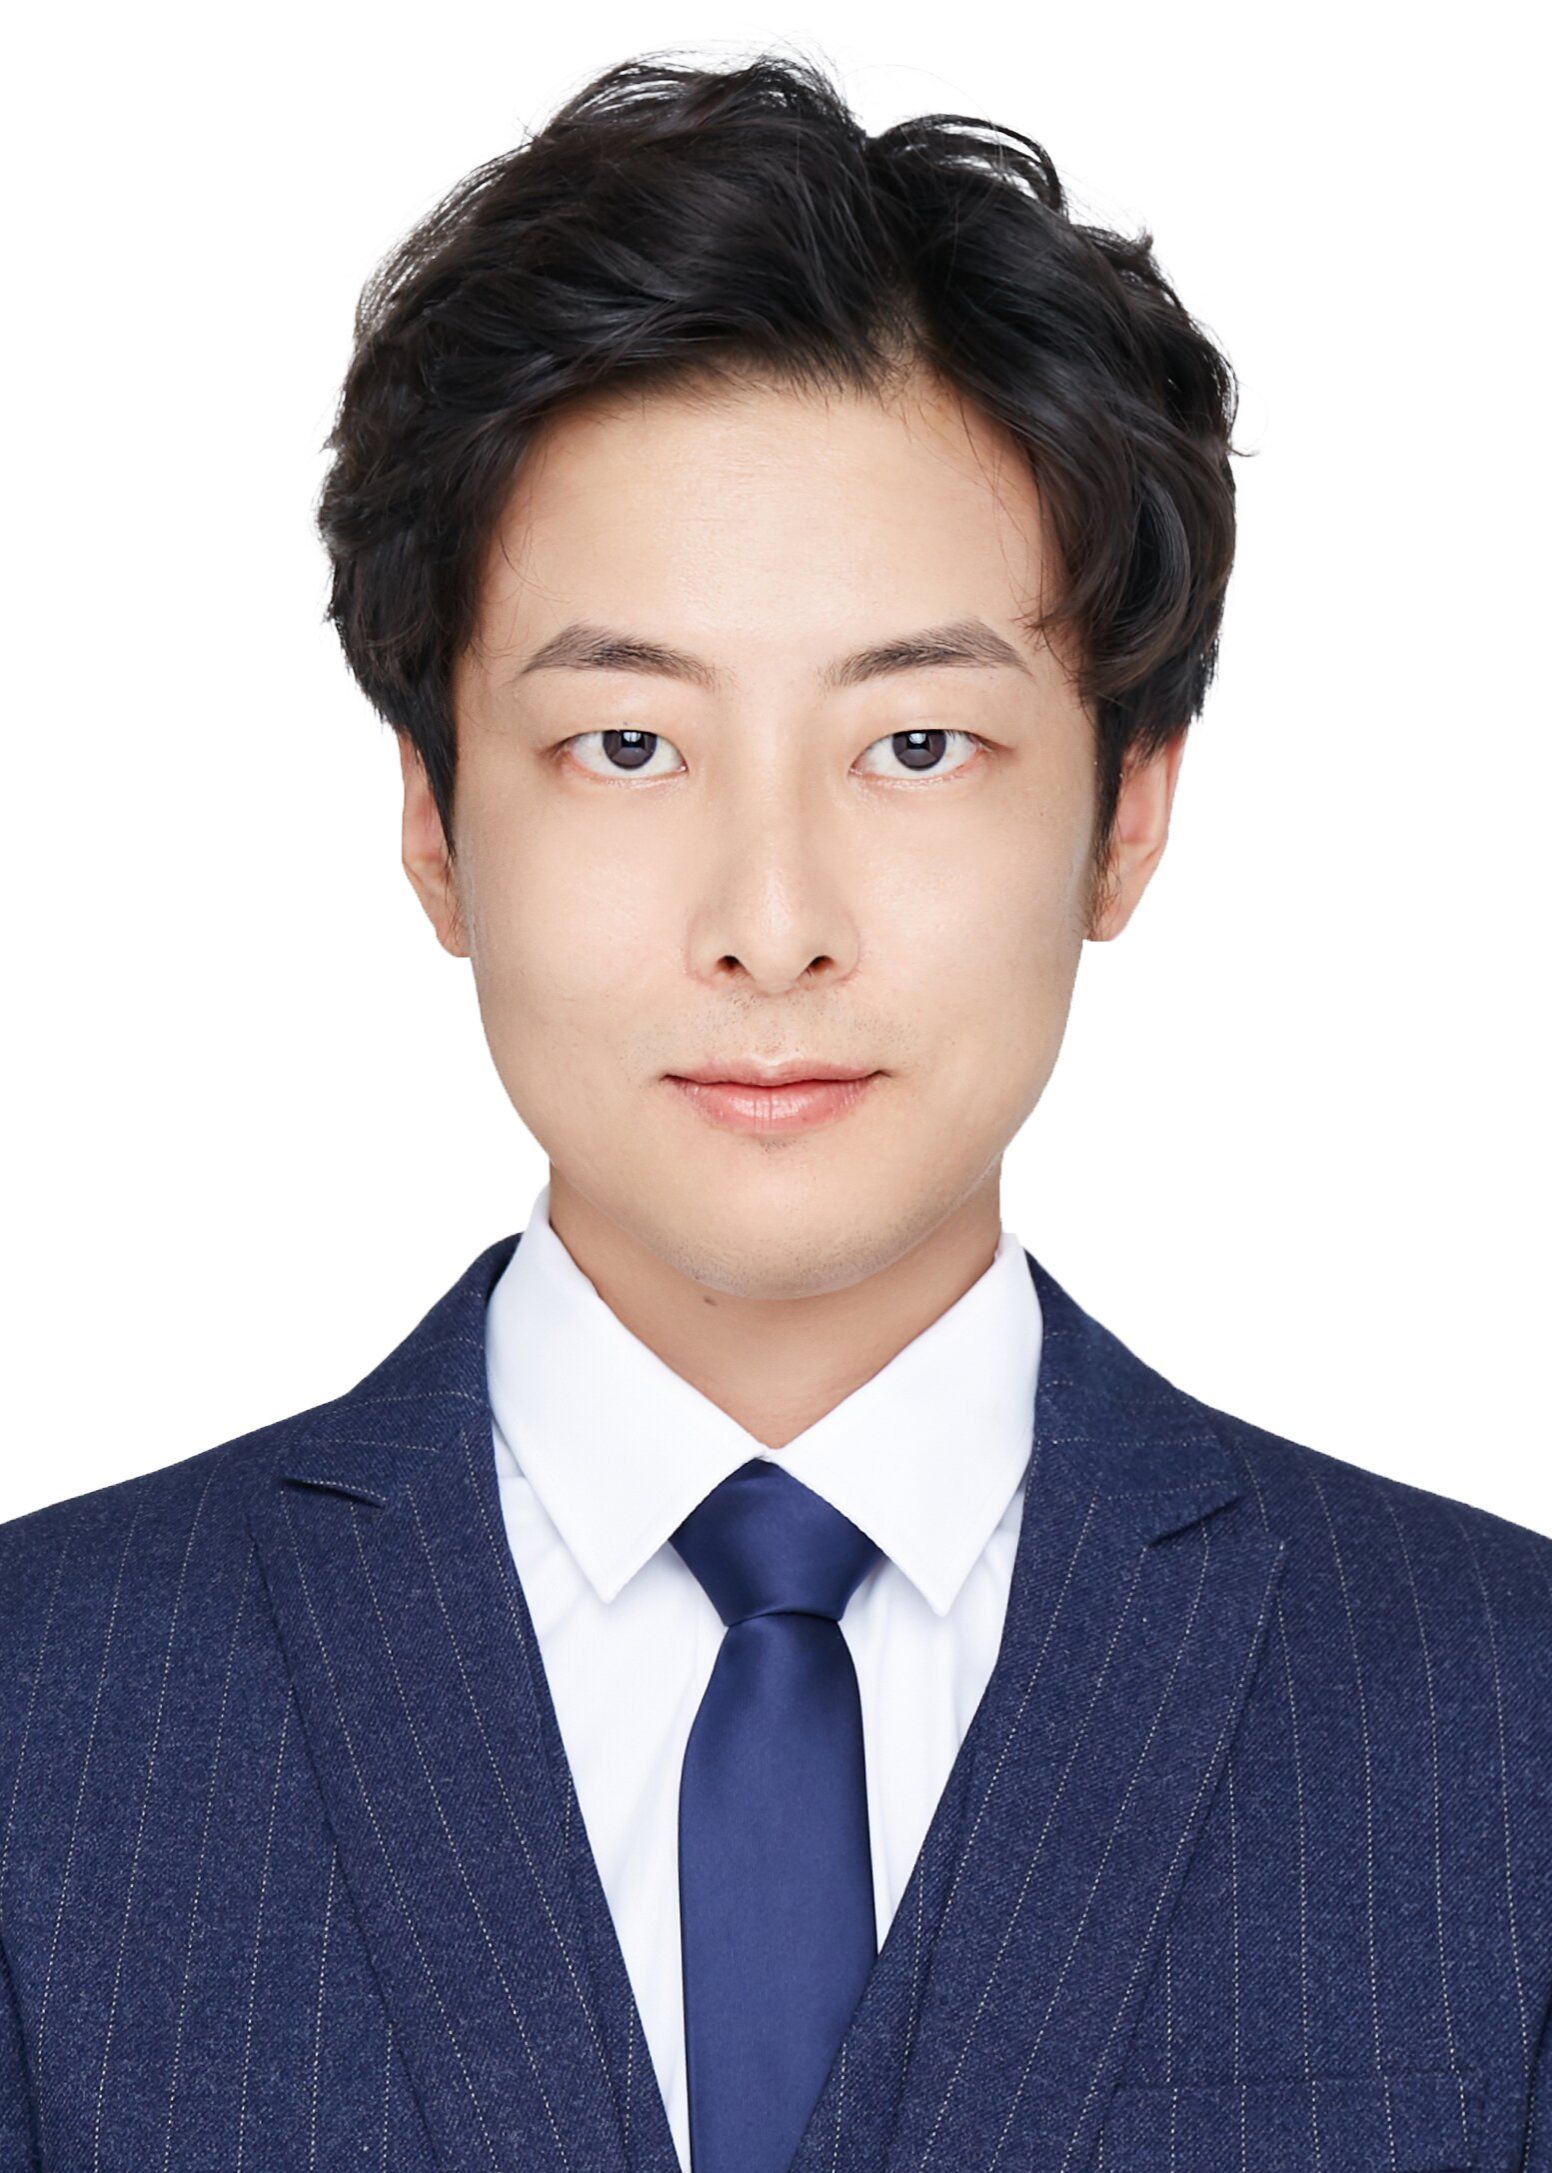
王昆仑,男,安徽阜阳,中共党员,博士毕业于上海财经大学概率论与数理金融专业,上海市优秀毕业生。主要从事公司金融、绿色金融、模糊不确定下动态规划、复杂金融衍生品定价的理论与研究工作,主持横向科研、教研、学科竞赛项目多项。在本领域国际期刊发表多篇学术论文(SCI,SSCI,EI期刊)。讲授金融工程、抽样技术、风险管理、国民经济核算等课程。
一、教育背景
2021.09-2025.07上海财经大学,概率论与数理金融专业,博士
2017.09-2020.07安徽工程大学,概率论与数理金融专业,硕士
2013.09-2017.07安徽工程大学,金融工程专业,本科
二、工作经历
2020.08-2021.05中国建设银行芜湖市分行,正式员工
三、发表论文情况
[1]Kunlun Wang,Junmei Ma,Wei Xu*,Zhenyu Cui. Willow Tree Approach to Optimal Investment with Capital Restriction under Merton’s Jump Diffusion Model[J]. Journal of Derivatives, 2025, 33(1): 8-30.(SSCI)
[2]Kunkai Du, Jun Liu, Kunlun Wang,Qicheng Zhao*. Enterprise digital transformation and bond credit spreads: From the perspective of risk premium[J]. Economic Analysis and Policy, 2025.(SSCI)
[3]Kunlun Wang,Junmei Ma, Wei Xu*.Exact Simulation of the 3/2 Stochastic Volatility Model with Stochastic Jump Intensity[J]. International Journal of Computer Mathematics, 2025. (SCI)
[4]Kunlun Wang,Wei XuJunmei Ma*, Pei You.Willow Algorithm for Consumption Investment under Stochastic Volatility Model with Jump Diffusion[J]. International Journal of Applied Mathematics. 2025, 55(1): 34-44.(EI)
[5]Kunlun Wang, Chen Fei, Weiyin Fei. Optimal Contract for the Principal-agent under Knightian Uncertainty[J]. Journal of theOperations Research Society of China, 2020, 4(8): 637-654. (ESCI/EI)
四、主持项目情况
[1]跳模型下最优投资问题的应用研究(项目编号:2025KYQD0184),科研项目(自科),主持,到账经费:9(万元)
[2]利用投入产出模型分析安徽能源消费与经济高质量发展的关系研究(项目编号:HX2025149000);横向科研项目(社科),主持,到账经费:3.5(万元)
[3]安徽省乡村治理数智化水平综合评价研究(项目编号:2025FSSK18),横向科研项目(社科),主持,批准经费:0.5(万元)
五、联系方式
Email: 122795241@qq.com

 学院地址:安徽省阜阳市清河西路 678 号
 联系电话:0558-2596094
 电子邮箱:sxytj@fynu.edu.cn